
Check three things first
Your vested balance, the $1,000 and $7,000 force-out tiers, and what happens to an outstanding 401(k) loan.
What to do with a company retirement plan after you quit, get laid off or retire. Compare your four options, roll it over without a tax hit, avoid the 20% withholding trap, and spot the special cases that change the answer. Updated with current federal rules.
No sign-up required. Educational use only; not investment, tax or legal advice.
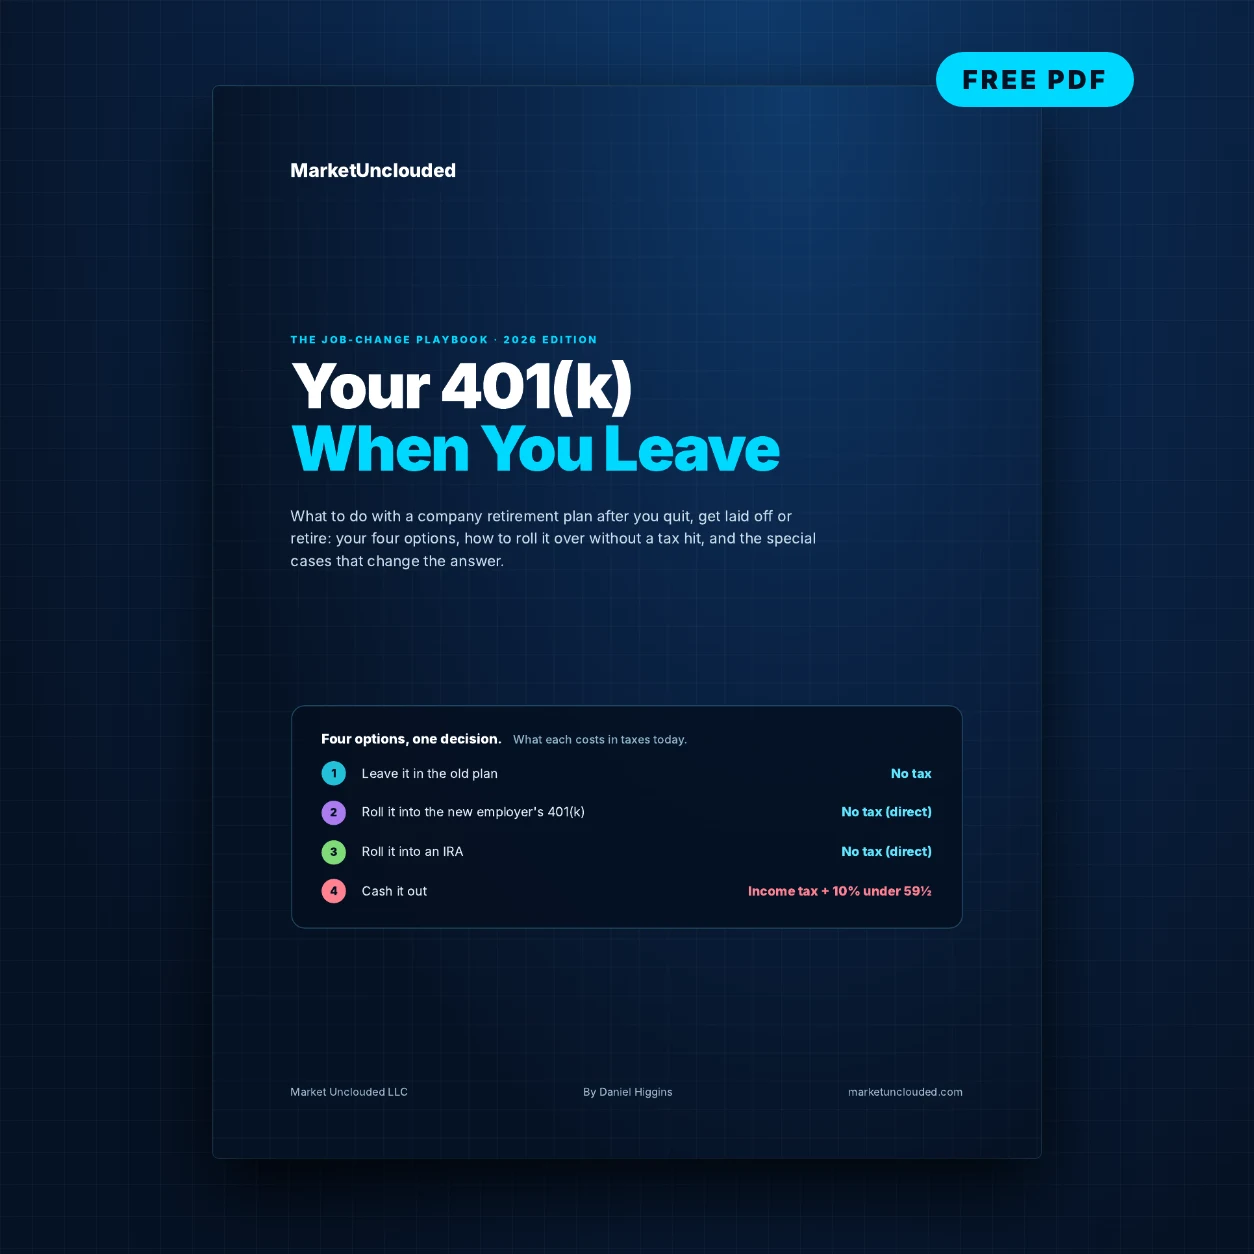
Most 401(k) mistakes after a job change come from a check made out to you, a forgotten loan or a rushed cash-out. The guide walks through each decision with tables, a worked example, key takeaways and a checklist.
Your vested balance, the $1,000 and $7,000 force-out tiers, and what happens to an outstanding 401(k) loan.
Leave it, roll it to a new plan, roll it to an IRA, or cash it out: when each fits and what it costs.
A worked $50,000 example: withholding, income tax, the 10% additional tax and the growth you give up.
Direct vs. 60-day rollovers, the 20% withholding trap, and a seven-step direct rollover walkthrough.
The Rule of 55, Roth 401(k) money, after-tax contributions, company stock (NUA) and backdoor Roth.
A side-by-side table of all four options, a simple way to choose, a job-change checklist and a glossary.
What each choice costs in taxes today, and what to watch. The guide covers when each one fits.
Simple, but easy to forget.
One account, if the new plan is good.
The most control.
At a 22% rate, before state tax.
Hypothetical illustration for education, not a recommendation. Option 4 assumes a $50,000 pre-tax balance, age 40, taxed at a 22% federal rate.
Leaving a job is busy enough. This guide helps you make one clean decision about the money you’ve already saved, without a surprise tax bill.
A downloadable educational guide, not personalized investment, tax or legal advice. Plan rules vary; read your plan’s Summary Plan Description. Federal rules are current as of November 2026.
Follow @MarketUnclouded to hear when the next free guide is released.